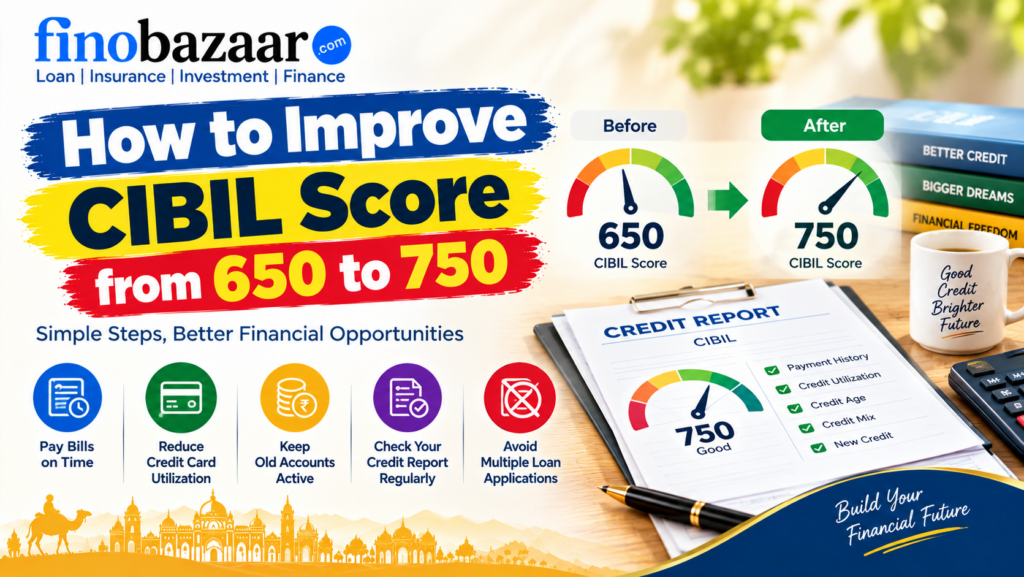
How to Improve CIBIL Score from 650 to 750
A CIBIL score of 650 may make it harder to qualify for some loans or credit cards on favourable terms. The good news is that you can work towards a score of 750 by building a consistent repayment record, lowering credit card balances, limiting unnecessary credit applications and correcting errors in your credit report.
There is no guaranteed shortcut or fixed timeline for moving from 650 to 750. Your progress depends on your existing credit history, overdue payments, outstanding balances, credit enquiries and how lenders report your information.
This guide explains how to improve your CIBIL score step by step, what mistakes to avoid and how to monitor your progress.
Table of Contents
- What does a CIBIL score of 650 mean?
- How to improve CIBIL score from 650 to 750
- A practical 90-day action plan
- How long does it take to improve your score?
- Common mistakes to avoid
- Frequently asked questions
What Does a CIBIL Score of 650 Mean?
A CIBIL score is a three-digit number ranging from 300 to 900, calculated using information in your credit report. Lenders may use it alongside your income, existing debt, employment or business profile and their own eligibility criteria when assessing a credit application.
A score of 650 is not an automatic rejection. However, it can signal that you should review your credit history and identify what may be holding your score back.
Before applying for another loan, check whether your report shows any of the following:
- Late or missed EMI payments.
- Overdue credit card balances.
- High credit utilisation.
- Several recent credit applications.
- Incorrect account balances or payment status.
- Accounts that do not belong to you.
- Loans incorrectly shown as overdue or unsettled.
Your credit report can help you identify which actions should come first.
How to Improve CIBIL Score from 650 to 750
1. Pay Every EMI and Credit Card Bill on Time
Payment history is an important factor in your credit profile. Late payments and defaults can hurt your score and may remain visible in your credit history.
What to do:
- Set up payment reminders before each EMI or credit card due date.
- Consider an auto-debit facility if you can keep enough money in your account.
- Pay at least the amount required by the due date, and aim to clear the full credit card statement balance whenever possible.
- If you have already missed a payment, contact the lender and arrange repayment according to your financial capacity.
Paying only the minimum amount due may help you avoid a late payment in some circumstances, but the remaining balance can continue to attract interest. It is not a long-term debt management strategy.
2. Reduce Your Credit Card Utilisation
Credit utilisation is the portion of your available credit limit that you are using. A high balance relative to your limit may negatively affect your credit profile.
Illustrative example:
| Credit card limit | Outstanding balance | Utilisation |
|---|---|---|
| ₹1,00,000 | ₹80,000 | 80% |
| ₹1,00,000 | ₹40,000 | 40% |
| ₹1,00,000 | ₹20,000 | 20% |
Formula:
Credit utilisation = Outstanding credit card balance ÷ Total credit limit × 100
In this example, reducing the balance from ₹80,000 to ₹20,000 lowers utilisation from 80% to 20%. This is a useful direction to work towards, not a guarantee of a particular score increase.
Try to reduce balances without missing essential expenses or taking an expensive new loan just to repay a credit card.
3. Clear Overdue Amounts and Bring Accounts Up to Date
If your report shows overdue EMIs or unpaid credit card dues, make a repayment plan based on your available budget.
Prioritise:
- Accounts that are currently overdue.
- Credit card balances with high interest costs.
- Payments needed to keep active loans up to date.
If you cannot pay the entire overdue amount immediately, speak with your lender about the available repayment options. Do not promise yourself a repayment schedule that your budget cannot support.
Paying overdue amounts does not guarantee that negative historical entries will disappear immediately. Make sure the lender reports the correct status after payment.
4. Check Your CIBIL Report for Errors
An error in your credit report may affect how lenders view your credit history. Review your personal information, account details, outstanding balances, payment history and credit enquiries.
Look for:
- A loan you never took.
- A payment incorrectly shown as missed.
- A closed account incorrectly shown as outstanding.
- An incorrect overdue amount.
- Duplicate accounts.
- A credit enquiry you do not recognise.
If you find a mistake, raise a dispute with CIBIL and contact the relevant lender. CIBIL generally cannot change lender-reported account information without confirmation from the credit institution.
Official resources:
- CIBIL credit education: https://www.cibil.com/
- CIBIL report correction guidance: https://myscore.cibil.com/CreditView/creditEducation_correctMistakes_newUX.page
Keep copies of payment receipts, closure letters, no-dues documents and complaint reference numbers.
5. Avoid Applying for Too Many Loans or Credit Cards
Each formal credit application may result in a lender enquiry on your credit report. Several applications within a short period can make lenders cautious and may affect your score.
Before applying:
- Check the lender’s eligibility criteria.
- Compare suitable products before submitting an application.
- Avoid applying to many lenders just to see which one approves you.
- Do not take a loan you do not need simply to try to increase your score.
Checking your own credit report is different from making multiple applications for new credit.
6. Keep Older Accounts in Good Standing
A longer, well-managed credit history can be useful. Avoid closing an account solely because you believe closing it will increase your score.
Before closing a credit card, consider its fees, your spending habits, the effect on your available credit and whether you can manage it responsibly. Never keep a costly or unsuitable product only for the sake of your score.
7. Maintain a Manageable Credit Mix
Your report may include secured loans, such as a home loan or vehicle loan, and unsecured credit, such as personal loans and credit cards.
There is no need to borrow more money just to create a particular credit mix. Taking on unnecessary debt can increase financial pressure. Focus on repaying existing obligations responsibly and borrowing only when there is a genuine need.
8. Monitor Your Report and Allow Time for Updates
Lenders submit account information to credit information companies periodically. As a result, a payment you made recently may not appear immediately in your report.
After paying a balance or correcting an error:
- Keep proof of payment or the lender’s confirmation.
- Allow time for the lender’s reporting cycle.
- Check whether the report reflects the updated information.
- Follow up with the lender or credit bureau if the information remains incorrect.
Repeatedly checking your score will not itself improve it. The important part is making sustainable changes to the underlying credit behaviour.
A Practical 90-Day Action Plan
The following plan is a way to organise your actions, not a promise that your score will reach 750 in 90 days.
| Period | What to do | Goal |
|---|---|---|
| Days 1–7 | Obtain and review your credit report; identify overdue amounts and errors | Understand the causes |
| Days 8–30 | Bring payments up to date where possible and reduce high-interest balances | Improve repayment discipline |
| Days 31–60 | Avoid unnecessary applications and continue reducing credit utilisation | Maintain stable credit behaviour |
| Days 61–90 | Review updated account information and follow up on unresolved errors | Check whether reported data is accurate |
Continue these habits after the first 90 days. The time required to reach a particular score varies by person.
How Long Does It Take to Improve CIBIL Score from 650 to 750?
There is no universal timeline. Some people may see changes after their account information is updated; others may need a longer period of consistent repayment behaviour.
Your progress may depend on:
- How recent and serious any missed payments were.
- Whether accounts are currently overdue.
- How much of your available credit you are using.
- The age and depth of your credit history.
- Whether inaccurate information needs correction.
- When lenders report updated information.
Be cautious of anyone promising a guaranteed score of 750 within a specific number of days or claiming that negative information can be removed for a fee without a valid basis.
Common Mistakes to Avoid
- Missing payments while trying to repay another account.
- Applying for several loans in a short period.
- Using most of the available credit card limit every month.
- Taking an unnecessary loan to build a credit score.
- Paying a company that promises guaranteed score improvement.
- Assuming that paying an overdue amount automatically erases past late payments.
- Ignoring errors in the credit report.
- Making a financial decision based on the score alone.
How to Check Your CIBIL Score and Report
Use the official CIBIL website to access the available score and credit report services. The Reserve Bank of India has directed credit information companies to provide individuals with one free full credit report, including the score, once per calendar year, subject to the prescribed authentication process.
Official RBI reference: https://www.rbi.org.in/commonperson/English/Scripts/Notification.aspx?Id=1884
Review your report before applying for a new credit product. A lender may consider several factors beyond your score.
Frequently Asked Questions
1. How can I improve my CIBIL score from 650 to 750?
Pay EMIs and credit card bills on time, reduce high credit utilisation, resolve overdue amounts, check your report for errors and avoid unnecessary credit applications. Results vary and are not guaranteed.
2. Can I increase my CIBIL score quickly?
There is no guaranteed quick fix. Correcting a genuine reporting error or lowering a high card balance may help once the updated information is reported, but the effect and timing vary.
3. How long does it take to increase a CIBIL score from 650 to 750?
There is no fixed timeline. It depends on the reason for the lower score, your credit history, repayment behaviour and when lenders update their records.
4. Does paying credit card dues improve my CIBIL score?
Reducing outstanding balances can improve credit utilisation, which is one factor in your credit profile. The exact score impact depends on your overall credit history and the information reported.
5. Will paying an overdue loan remove late payments from my report?
Not necessarily. Payment may update the account’s current status, but accurate historical payment information is not automatically erased simply because the amount is paid.
6. Does checking my own CIBIL score reduce it?
Checking your own report is generally treated as a self-check rather than a lender’s credit application enquiry. It is sensible to review your report periodically.
7. Should I close old credit cards to improve my score?
Not automatically. Consider fees, spending discipline, available credit and your overall financial situation before closing an account. Keep accounts only if they remain suitable and manageable.
8. Can a credit repair agency guarantee a CIBIL score of 750?
No legitimate service can guarantee a specific score increase. Be cautious of claims that promise guaranteed results or removal of accurate negative information.
9. Can I get a personal loan with a CIBIL score of 650?
Some lenders may consider applications with different score profiles, but approval depends on their eligibility rules, income, existing obligations, repayment history and other factors. Compare options carefully and avoid repeated applications.
10. What should I do if my CIBIL report shows a loan that is not mine?
Review the account details, raise a dispute with CIBIL and contact the lender concerned. Keep your supporting documents and complaint references until the issue is resolved.
Conclusion
Improving your CIBIL score from 650 to 750 starts with understanding your credit report and consistently managing your existing credit. Prioritise timely payments, lower outstanding card balances, correct genuine reporting errors and avoid unnecessary borrowing.
There is no guaranteed timeline, but responsible credit habits can help build a stronger credit profile over time.
Disclaimer: This article is for general educational purposes and is not a guarantee of loan approval or a particular credit score. Review your own credit report and consult your lender for account-specific concerns.