What Happens If Your Credit Card Bill Is Paid 5 Days Late?
If you pay your credit card bill five days after the due date in India, you may face late-payment charges, finance charges, and possible credit-bureau reporting, depending on your account and the card issuer’s terms. Paying the bill late does not automatically mean your credit score will fall by a fixed number of points, but the delay should not be ignored.
The Reserve Bank of India (RBI) says card issuers may levy late-payment charges or report an account as past due to credit information companies when it remains past due for more than three days. The days past due are counted from the due date shown on the statement. Therefore, a payment made five days late can cross that threshold. Read the RBI’s credit card directions.
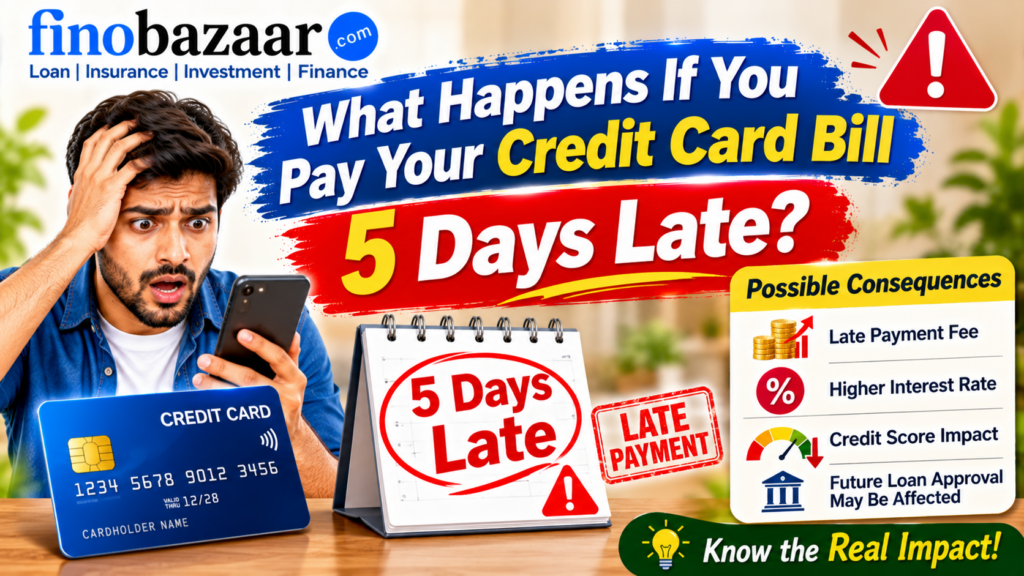
What Happens If You Pay Your Credit Card Bill 5 Days Late?
Here are the main consequences to understand.
1. You may be charged a late-payment fee
Your card issuer may charge a late-payment fee if the account remains past due for more than three days, subject to the applicable RBI rules and your card terms. The exact fee depends on the issuer, the outstanding amount, and the fee schedule.
RBI directions also state that late-payment and related charges must be levied on the outstanding amount after the due date, rather than automatically on the entire statement amount. Official RBI reference.
Example: Suppose your statement shows ₹12,000 due on 10 October, but your payment is credited on 15 October. That is five calendar days after the due date. If the account remained unpaid during that period, a late fee may apply under your issuer’s terms. The actual charge cannot be determined without your card’s fee schedule and account details.
2. Interest or finance charges may apply
Paying after the due date can affect your interest-free period. If you did not clear the total amount due by the deadline, the issuer may charge interest on the outstanding amount, potentially from the date of the transactions, after adjusting for payments, refunds, and reversed transactions as they are credited.
This means the cost may not be limited to interest for just five days. The calculation depends on your card’s terms and transaction history.
RBI’s official credit card FAQs explain that when the total amount due is not cleared by the payment due date, the interest-free credit period is lost and interest may be charged on the outstanding amount. Read the RBI FAQs.
3. Your credit report may show a past-due account
RBI rules allow a card issuer to report an account as past due to credit information companies when it remains past due for more than three days. The count is calculated from the due date shown on your statement.
A five-day delay can therefore cross the reporting threshold. However, this does not guarantee that every five-day delay will appear in your credit report in exactly the same way or immediately. The timing and treatment depend on the issuer’s reporting and the account’s status.
4. Your credit score may be affected
A late payment may affect your credit profile if it is reported. There is no reliable universal rule that says a five-day delay will reduce every person’s score by a particular number of points.
If you have already paid, check your next statement and credit report when the information has had time to update. If the reported information is inaccurate, contact the card issuer and the relevant credit bureau to request a correction.
5. Your next bill may include additional charges
Your next statement may include unpaid balances, finance charges, applicable taxes or fees, and any new transactions. Paying the bill late can therefore make the next amount due higher than expected.
Check the statement’s transaction details and charge breakdown instead of assuming that the amount you paid has settled every outstanding item.
Example: Credit Card Bill Paid Five Days Late
Consider this hypothetical situation:
| Detail | Example |
|---|---|
| Statement amount due | ₹12,000 |
| Payment due date | 10 October |
| Payment credited | 15 October |
| Delay | 5 calendar days |
| Late fee | Depends on card terms |
| Finance charges | Depends on the card’s rate and transaction history |
| Credit score impact | Not possible to predict from the delay alone |
This example illustrates the timing, not the exact penalty. The precise cost cannot be calculated from the delay alone because the card issuer’s fee schedule, interest rate, transaction dates, outstanding balance, and payment-crediting date all matter.
What Should You Do If You Have Paid Your Credit Card Bill Late?
Follow these steps to reduce the chance of further problems.
Step 1: Pay the outstanding amount as soon as possible
If the bill remains unpaid, pay the amount you owe as soon as you can. If you have made a payment already, verify that it has been credited to the card account. Remember that paying after the due date may not reverse charges that have already become applicable.
Step 2: Check the next statement
Look for late-payment fees, finance charges, taxes, and any remaining unpaid balance. Compare the charges with the issuer’s official Most Important Terms and Conditions (MITC) and schedule of charges.
Step 3: Contact your card issuer
If this was an accidental delay or a one-off issue, contact the issuer through its official customer-service channel. Explain what happened and ask whether a fee reversal or waiver is available. A waiver is not guaranteed.
If you paid before the deadline but the payment was credited later, keep the payment confirmation and ask the issuer to investigate the transaction and crediting time.
Step 4: Check your credit report
After allowing time for reporting, review your credit report for accuracy. If a payment is incorrectly shown as unpaid or past due, raise a dispute with the issuer and the credit bureau. Keep your payment receipt and complaint reference number.
Step 5: Set up a reminder or automatic payment
Set a reminder a few days before the next due date. If you use automatic payment, ensure that the linked bank account has enough funds and that the payment instruction is active. Do not assume a scheduled instruction succeeded without checking the confirmation.
How Can You Avoid Credit Card Late-Payment Charges?
- Pay the full statement amount by the due date whenever possible.
- Make the payment early enough to allow for processing.
- Check that the payment is credited, not merely initiated.
- Keep enough money in the linked account if using auto-debit.
- Review the card issuer’s fee schedule and finance-charge terms.
- Contact the issuer promptly if a payment fails or a charge appears incorrect.
Paying only the minimum amount due is not the same as paying the full bill. Even when the minimum payment is made, the remaining balance may attract interest and the interest-free period may be suspended under the card’s terms.
Frequently Asked Questions
1. Will I be charged a late fee if I pay my credit card bill five days late?
A late fee may apply because RBI rules permit late-payment charges when an account remains past due for more than three days. The amount depends on your card issuer’s terms and the outstanding amount.
2. Will paying my credit card bill five days late reduce my CIBIL score?
It may affect your credit profile if the issuer reports the account as past due, but a fixed score reduction cannot be predicted. The result depends on your credit report, account status, and reporting.
3. Is there a three-day grace period for credit card payments in India?
RBI rules set a threshold of more than three days past due before an issuer may report the account as past due or levy late-payment charges. This should not be treated as an extension of the payment due date or as a guaranteed interest-free grace period. The count is calculated from the due date shown on the statement.
4. Will I have to pay interest if I clear the bill five days late?
Finance charges may apply if you did not clear the total amount due by the deadline. The interest-free period may be lost, and the issuer may calculate interest on the outstanding amount according to the card’s terms.
5. What if I paid on time but the payment was credited five days later?
Keep the payment confirmation and contact the card issuer immediately. Ask it to check the payment initiation date, crediting date, and any charges. Whether the charge can be reversed depends on the circumstances and the issuer’s investigation.
6. Can I ask the bank to waive a late-payment fee?
Yes, you can request a waiver, especially if the delay was accidental or unusual. The issuer may approve or reject the request; a waiver is not guaranteed. Ask for a written confirmation if it is approved.
7. When should I check my credit report after a late payment?
Check after allowing time for the issuer’s reporting cycle and the credit bureau’s update process. There is no single guaranteed update date for every issuer. If the report remains inaccurate, raise a dispute with supporting evidence.
8. What should I do if I cannot afford the full credit card bill?
Pay what you can as soon as possible and contact the issuer to discuss available repayment options. Before agreeing to an EMI conversion or another arrangement, review the interest rate, fees, tenure, and total repayment cost.
Conclusion
If you pay your credit card bill five days late, you may face late-payment charges, finance charges, and possible credit-bureau reporting. Under RBI rules, an account remaining past due for more than three days can cross the threshold for late-payment charges or reporting, with the count calculated from the statement’s due date.
Pay the outstanding amount promptly, confirm that the payment has been credited, review your next statement, and contact your issuer if anything looks incorrect. To avoid future problems, schedule payment early and verify that it has gone through.
Disclaimer: This article is for general financial education and is not personalised financial advice. Actual charges and credit-report outcomes depend on the applicable RBI rules, your card issuer’s terms, payment-crediting details, and account status. Always check your card statement and official issuer documents before making a decision.